
Donations Under Section 80G And 80GGA of Income Tax Act
Section 80G of the Indian Income Tax Act allows you to claim a tax deduction for donations to any charity organisation, whereas Section 80GGA allows you to claim a tax deduction for contributions to research and rural development.
Schedule a Call Back
150+ NGO, 80G and 12A assignments since 2018
Clients include Pramiti Education & Knowledge Society, Jeevan Aadhar Charitable Trust, Nimal Maula Foundation, Sudarshan Munjal Trust, World Mission Society Church of God, 3Rd Eye Foundation, Khayerpati Mukunda Lal Education Society, Hopeful Hearts Foundation, Aarambh Development Foundation, Karmaa Foundation, Garapati Moshe Memorial Trust, One Globe Foundation (12 of 100+ served since 2018).
A few more clients we've served in this industryHide the list
- Non-profits and education
- Pramiti Education & Knowledge Society · Jeevan Aadhar Charitable Trust · Nimal Maula Foundation · Sudarshan Munjal Trust · World Mission Society Church of God · 3Rd Eye Foundation · Khayerpati Mukunda Lal Education Society · Hopeful Hearts Foundation · Aarambh Development Foundation · Karmaa Foundation · Garapati Moshe Memorial Trust · One Globe Foundation · Samarpit Sewa Sansthan · Sri Vidya Vikas Foundation · Aaruh Foundation
- More clients
- Witcorp India Advisors · SLS Sungrace Power · Bharateeya Sanathana Aadhunika Dharma Pariposhanam Trust · D P Sarawgi Foundation · Dyutima Foundation · Ileep Foundation · Kannan Animal Welfare Foundation · Maa Annapurna Sewa Trust · Ramani Education and Charity Trust · Real Smile Foundation · REY Foundation · S.N. Educational Trust · Saans Foundation · Sahara Education and Welfare Foundation · Shanti Samarpan Foundation · Shiv Bhavani Seva Trust · Shivani Seva Society · Shri Ravinder Joshi Charitable Foundation · Shri Shakiti Charitable Trust · Shri Varni Siksha Prasar Samiti · Smyle Mysha Welfare Society · Social Action and Voices for Integrated Development Trust · Srinivasa Perumal Trust · Thisai Charitable Trust
Section 80G of the Code:
Section 80G of the Internal Revenue Code allows contributions to relief funds and humanitarian organisations to be deducted. On the other hand, Section 80G does not apply to all donations. Contributions to specific trusts are the only ones that are tax-deductible. This deduction is available to any taxpayer, whether a person, a corporation, a partnership, or another entity.
Claim for an 80G Deduction:
To claim this deduction, you must include the following information on your tax return.
- Contribution Amount
- Name
- Pan Card
- Address
Tax Exemption under Section 80G:
Any donation to a rescue fund or charity is tax deductible. This is a reduction that can be used to net taxable revenue calculations. Deductions for charitable contributions, on the other hand, are subject to the following restrictions:
- Not every donation qualifies for a complete tax deduction. When applying for a deduction, the assessee must follow the organization's eligibility requirements.
- Deductions will be sought by specific taxpayers, Indian corporations, alliance firms, and other assessees.
- A tax deduction is not available for cash contributions in excess of Rs 2,000.
- Any in-kind contribution, such as clothing, food, or drugs, is neither tax-deductible nor beneficial.
The amount of the contribution is determined by the criterion for qualifying. Section 80G permits you to deduct either 100% or 50% of your income, with or without limitations.
80G Donation Limit:
Not every donation is eligible for a full deduction under section 80G. It depends on whether or not the organisation to which the donation is made is eligible. The eligibility of the organisation determines the tax benefit. Furthermore, the deduction could be 100% or 50%, with or without restrictions.
The qualifying amount is the amount that can be deducted from a contribution. Any assessee must carefully measure the qualified number to avoid any falsification of the income tax return.
Under Section 80G, donations are eligible for a one-hundred percent deduction with no qualifying limits.
- National Defence Fund by the Central Government.
- Prime Minister National Relief Fund.
- National Foundation for Communal Harmony.
- A University/educational institution of National eminence.
- Zila Saksharta Samiti in districts under the chairmanship of the collector of that district.
- Fund by State Government for medical relief to the poor.
- National Illness Assistance Fund.
- National Blood Transfusion Council.
- National Sports Fund.
- National Cultural Fund.
- National Children’s Fund.
- Chief Minister’s Earthquake Relief Fund.
- Prime Minister’s Armenia Earthquake Relief Fund.
- Africa (Public Contributions – India) Fund.
- Swachh Bharat Kosh (applicable from FY 2014-15).
- Clean Ganga Fund (applicable from FY 2014-15).
- National Fund for Control of Drug Abuse (applicable from FY 2015-16).
Section 80 of the GGA:
Section 80GGA allows you to deduct contributions to scientific research or agricultural development. All assessments are eligible for this deduction, with the exception of those who have an income (or loss) from a business or occupation. Gifts can be made by check, draught, or cash; however, cash donations over Rs 10,000 are not eligible for tax deductions. 100% of the money donated or contributed is eligible for a tax return.
Donations that fall within Section 80GGA are Tax-deductible:
- Any sum paid to a research organisation conducting scientific research, or to a college, university, or other institution for the purpose of scientific research, as long as the quantity is permitted by the specified authority under section 35. (1). (ii)
- Payments to a research organisation conducting social scientific or statistical research, as well as payments to a college, university, or other institution for the same purpose, must be authorised by the specified authority under section 35. (1).(iii)
- Amount charged to a registered agency or group that participates in a section 35CCA-approved rural development initiative.
- Amount paid to an accredited agency or organisation for the goal of educating people about rural development programmes and encouraging them to participate.
- Amount charged to a public sector corporation, a local government, or an authorised agency or organisation to carry out projects or schemes approved under section 35AC.
Any expenses that are deductible under section 80GGA are not deductible under any other provision of the tax code.
FAQs about Section 80G and 80GGA Donations:
In terms of income tax, what does 80GG mean? What is the maximum amount of rent that can be charged under Section 80GG?
Even if your payment does not include an HRA portion or if you are a self-employed employee with non-salary income, 80GG allows you to deduct rent paid. You do not own any rental housing in your place of residence to claim the exclusion under 80GG.
What is the 80GG formula? What is the best way to obtain 80GG?
The lowest of the following 80GG deductions will be permitted:
- Monthly income of 5,000 rupees.
- Long-term capital gains, short-term capital gains under section 111A, income under section 115A or 115D, and exemptions under sections 80C to 80U account for 25% of the total adjusted income.
- Actual rent minus 10% of gross income.
Who can take use of the 80GG deduction?
Employees in the informal sector or self-employed individuals who do not get HRA as part of their salaries are eligible for an 80GG deduction. A person who owns a residence in the city where they live should not take advantage of this deduction.
Is it possible to say 80GG and HRA at the same time?
Individuals who pay rent but do not earn a dwelling rent payment are ineligible for the section 80GG deduction. The person, partner, or children must not own a house in the place of employment in order to claim this deduction.
About the Author

Shamshad Alam
Head - Digital MarketingExperienced Digital Marketer with a demonstrated history of working in the Internet industry. He likes to write about the latest technology trends, Skilled in Digital Marketing likes. Search Engine Optimization, SMO, SEM, PPC, Content Writing, and, Designing, etc.
Related articles
Pvt Ltd vs LLP vs OPC: Which Is the Best Business Structure in India?
2026-10-08
MCA Introduces New CSR Funding Route Through Zero-Coupon Zero-Principal Instruments
2026-05-30
How to Register a Startup in India (2026): A Step-by-Step Legal & Compliance Guide
2026-05-07
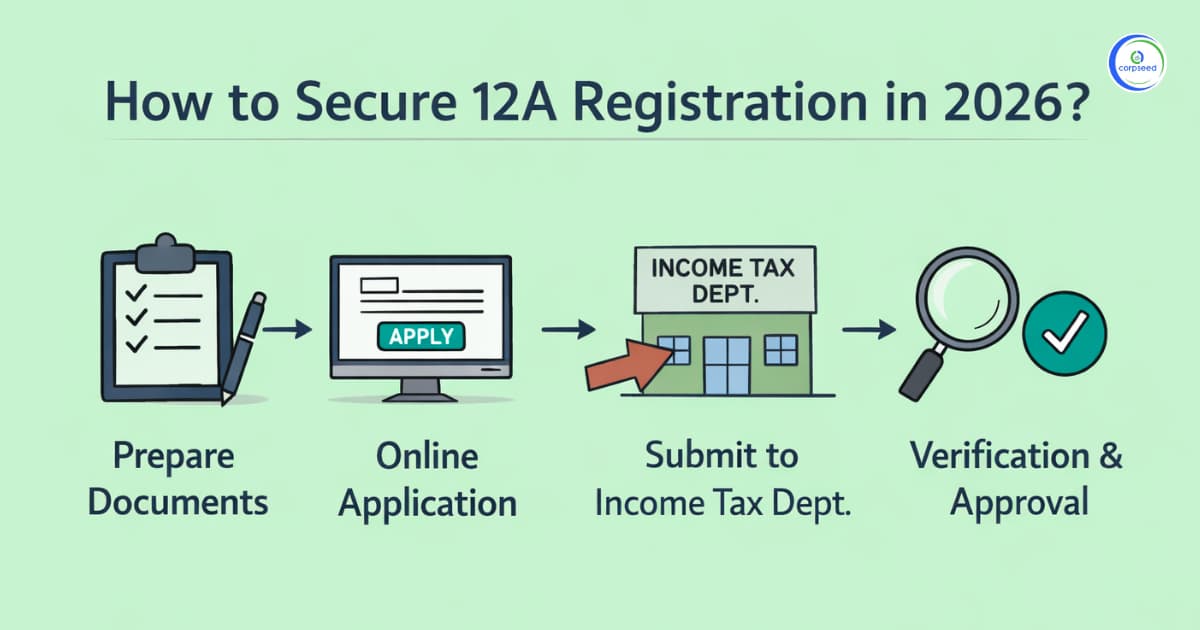
How to Secure 12A Registration in 2026?
2026-04-18
MCA Invites Stakeholders' Feedback to Simplify SPICe+ Part B Resubmission and Linked Forms
2026-01-03
Annual Compliance Checklist For Private Limited Companies And LLPs In India
2025-12-31